RDL 33/2026 rolls out DANA Adam aid: tax exemptions, 5,000 euros for the self-employed and emergency contracting
Royal Decree-Law 33/2026 sets IBI and income tax exemptions, aid of 5,000 and 10,000 euros and 74.5 million euros in infrastructure after DANA Adam.
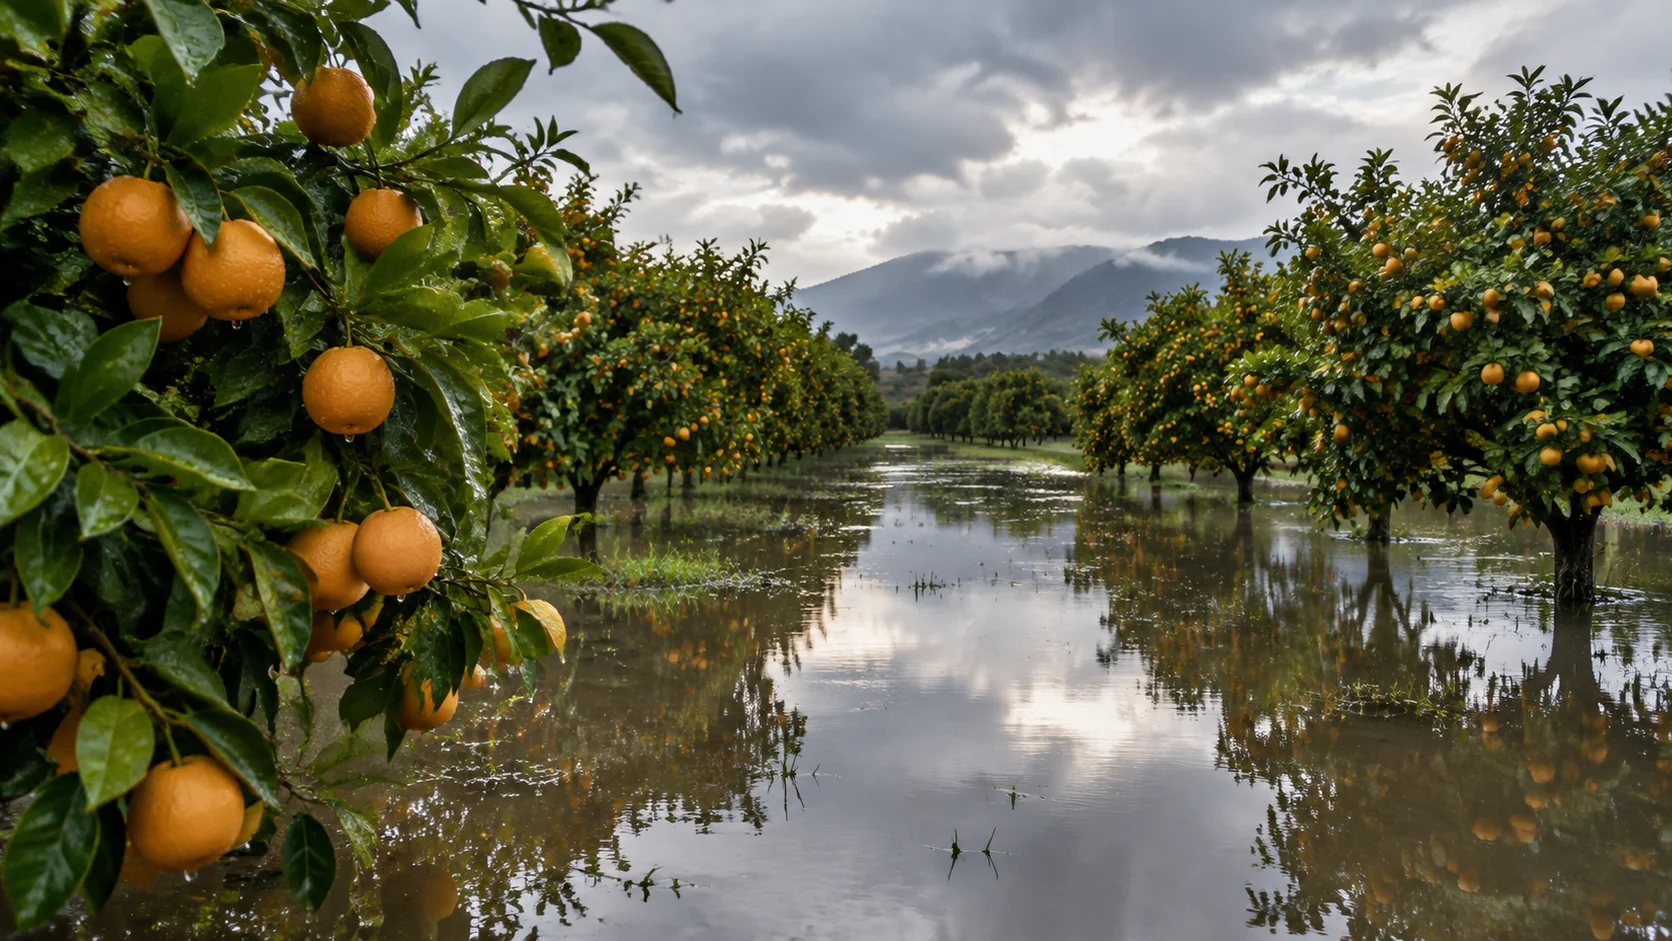
Royal Decree-Law 33/2026, of 10 November, adopts a package of urgent measures in response to the damage caused by the floods and other events between 17 and 19 October 2026 as a result of the DANA (isolated high-altitude depression) named Adam. Published in the Official State Gazette of 11 November and in force since the following day, the rule is structured in five chapters and thirty articles, accompanied by seven additional and five final provisions, and combines agricultural aid, emergency hydraulic works, tax benefits and direct support for retail, tourism and hospitality in the Comunitat Valenciana.
The economic scale shows in three figures: 70 million euros of extraordinary credit for emergency actions on the coast, 3 million for the Júcar Water Authority and 1.5 million for the Segura Water Authority, on top of the fixed-amount aid for local businesses and the 2026 tax exemptions.
Agricultural chapter: compensating the soil's loss of productive capacity
Chapter II concentrates measures for farms in the affected area, with special attention to the crops of greatest economic weight: citrus, vegetables and persimmon. The approach is technical: it is not limited to visible damage but seeks to compensate the consequences of altered soil conditions, persistent water saturation and the resulting loss of productive capacity, factors that can cause delays in farm work, root asphyxia, pathogen proliferation and a significant increase in plant-health risks.
The first additional provision adds an extraordinary aid for parcels from the October 2024 DANA where restoration is materially impossible or manifestly disproportionate: a minimal fraction, around 0.1% of the 26,261 hectares acted upon under Royal Decree-Law 7/2024, whose holders, if they are primary producers, will receive compensation allowing them to continue their activity.
Hydraulic infrastructure and coastline through the emergency procedure
Chapter III enables the emergency procedure of article 120 of Ley 9/2017, of 8 November, on Public Sector Contracts, for the repair of damage to the hydraulic public domain and the repair, rehabilitation and improvement of affected state-owned hydraulic infrastructure. The same channel applies to actions to protect and restore the maritime-terrestrial public domain to recover the coast's response capacity against erosion, together with other actions from the National Strategic Plan for the Protection of the Spanish Coast needed for the resilience of the Valencian shoreline.
The decree also reinforces the staff of the Ministry for Ecological Transition, of the Júcar and Segura Water Authorities and of the coast demarcation of the affected area, and extends the deadline for starting the performance of services under article 120.1.c) of the LCSP for actions declared an emergency in the three months following the rule's entry into force.
Tax benefits: IBI, IAE, personal income tax and cadastral fees
Chapter IV deploys the tax front. Exemptions from the Real Estate Tax (IBI) and reductions in the Economic Activities Tax (IAE) for 2026 are granted for properties directly damaged by the DANA, with the possibility for those who already paid the year's bills to request a refund. So that municipalities do not lose revenue, the State Treasury will compensate those tax benefits to the affected local entities.
The cadastral accreditation fee is also waived for certificates issued by the Directorate-General of the Cadastre on properties in the municipalities covered by the decree. And in personal income tax, the net yield indices of Order HAC/1425/2025, of 9 December (the 2026 development of the objective estimation method for income tax and the simplified VAT regime), are reduced for agricultural activities carried out in the affected area.
Local entities and regional financing
On budgetary stability, the affected local entities may use their 2025, 2026 and 2027 surpluses to finance financially sustainable investments, with exceptions from certain general requirements, provided the investments are directly related to the disaster's damage, whether to repair it or to prevent future damage from similar events. The treatment extends to such investments started in 2026 and financed with the 2025 surplus, under Royal Decree-Law 13/2026, of 2 June.
For the Comunitat Valenciana, the financing of extraordinary DANA Adam response expenses is enabled through the allocation in 2026 and 2027 of resources from the Autonomous Communities Financing Fund, with separate accounting and specific treatment for expenditure-rule purposes. The fourth additional provision extends that scheme to the expenses of the 2024 DANA and of the floods between 10 November 2025 and 9 February 2026.
Fixed-amount aid: 5,000 euros for the self-employed and 10,000 for SMEs
Chapter V creates a support measure for retail, tourism and hospitality in the Comunitat Valenciana in the form of a fixed-amount grant: 5,000 euros for self-employed workers and 10,000 euros for small and medium-sized enterprises and entities without legal personality that meet the requirements. The fixed amount responds to the need to provide immediate support without conditioning the award on an individualized expert assessment of the damage, while keeping controls on the establishment's actual affected status and on EU state-aid rules.
Management, coordination and execution are entrusted to the Official Chamber of Commerce, Industry, Services and Navigation of Spain through a direct subsidy, including the application and justification of the funds.
Insurance Compensation Consortium and interim staff
The fifth additional provision establishes an exceptional and temporary emergency contracting regime to reinforce the expert, medical and technical capacity of the Insurance Compensation Consortium in the face of the volume of compensation claims. And the sixth and seventh provisions allow deferring the termination of interim civil servants appointed for the response to adverse weather events in the Government delegations of Andalucía and Extremadura, as well as those designated for response tasks to the 2024 DANA in Valencia.
The state tax front: the general exemption for disaster aid
The second final provision amends Ley 35/2006, of 28 November, on personal income tax, to declare exempt the public aid for personal damage derived from fire, flood, subsidence, volcanic eruption or other natural causes, provided the area has previously been declared seriously affected by a civil protection emergency under Ley 17/2015, of 9 July. With effect from 1 January 2025, the exemption extends to aid granted by autonomous communities and local entities when their beneficiaries and requirements are identical or analogous to those of an exempt state aid for the same catastrophe.
For advisers with clients in the area, the work map is broad: IBI and IAE 2026 refunds, reduction of objective-estimation indices, applications for the fixed-amount aid before the Chamber and follow-up of Consortium files. Context on administrative disaster response in our opinion piece on the suspension of procedural deadlines in catastrophes, more recent regulation in actualidad and resources for the practice in abogacía y autónomos.
FAQ
What direct aid does RDL 33/2026 provide for the self-employed and SMEs? Fixed-amount grants of 5,000 euros for self-employed workers and 10,000 euros for SMEs and entities without legal personality in retail, tourism and hospitality in the Comunitat Valenciana, managed by the Chamber of Spain.
What tax benefits does it include? IBI exemption and IAE reduction for 2026 for damaged properties (with refunds if already paid), waiver of the cadastral accreditation fee, reduced objective-estimation net yield indices for agriculture in the area, and a general exemption for public aid for personal damage in declared catastrophes.
How much goes to infrastructure? 70 million euros for emergency coastal actions, 3 million for the Júcar Water Authority and 1.5 million for the Segura Water Authority, processed through the emergency procedure of article 120 of the LCSP.
Since when is it in force? Since 12 November 2026, the day after its publication in the BOE.
Sources
- Royal Decree-Law 33/2026, of 10 November (BOE-A-2026-23602, BOE no. 281, of 11 November 2026), consulted 13 November 2026.
Fuentes
- Source. Accessed 13 November 2026.
The specific data in this article come from the official sources cited.